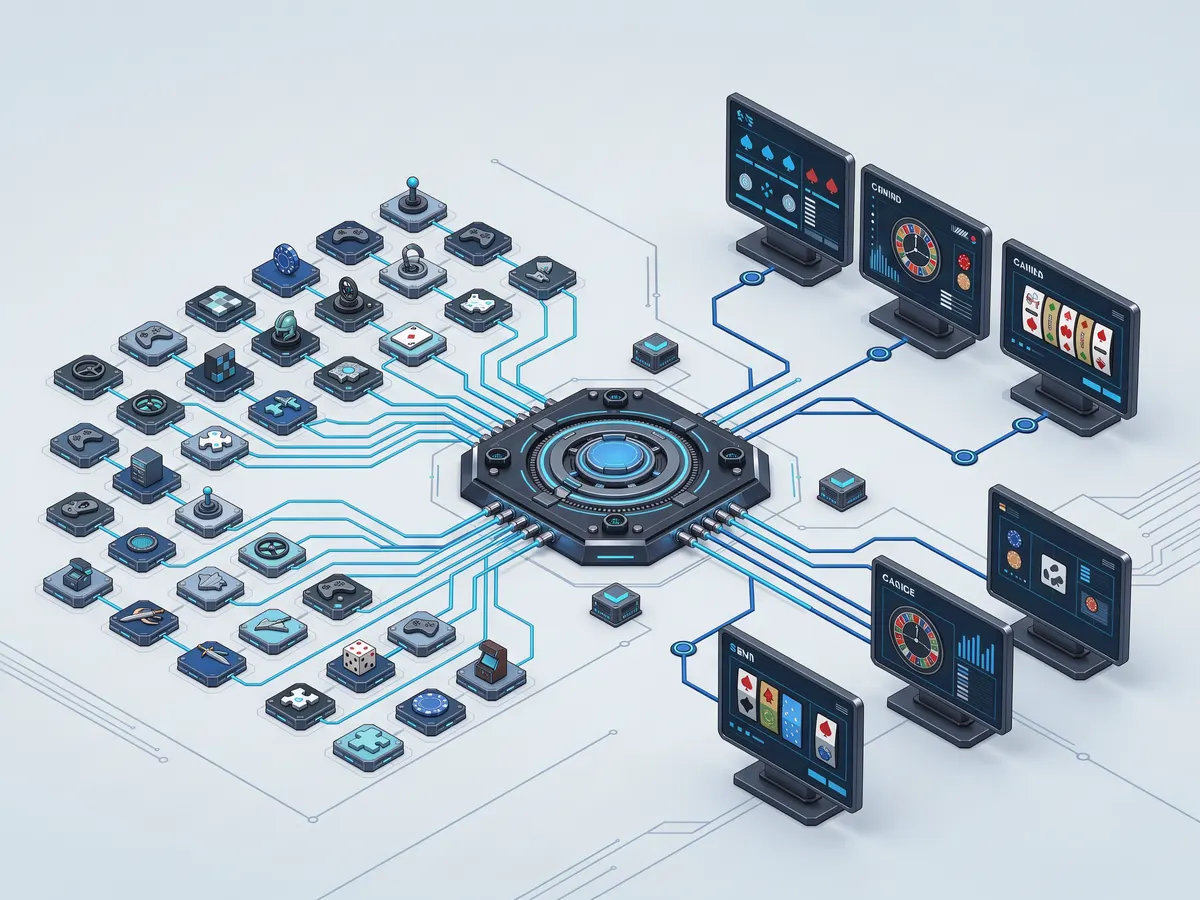
One contract, signed in October 2026, handed Stake a route to more than 45,000 casino games from over 360 providers. Not 45,000 negotiations. One integration. That gap between the number of games and the number of deals is the whole point of casino game aggregation, and it explains more about what you see in an online casino lobby than almost anything else in the industry.
What casino game aggregation actually means
Casino game aggregation is a single supplier integrating hundreds of game studios into one technical feed, which an operator connects to once and then draws its entire game library from. The operator gets one API, one contract, one reporting pipeline, and access to every studio the aggregator already carries.
The wholesale analogy holds up well. A direct studio deal is a shop negotiating with each bakery individually: price, delivery, packaging, invoicing, all bespoke. An aggregator is the distributor who already has agreements with every bakery in the region and sells from one catalogue. The shop still decides what goes on the shelf, but it no longer has to build a relationship with each baker to find out.
That last part matters. Aggregation does not mean an operator switches on all 45,000 games. It means it can, in principle, switch on any of them, usually within days rather than months.
What Stake and EveryMatrix actually announced
EveryMatrix will supply Stake with casino content aggregation across regulated markets, with North America, Latin America and Europe named as the growth focus. The reported scope: access to EveryMatrix’s aggregation catalogue of 45,000-plus casino, live casino, crash, table and instant games from more than 360 providers, through a single integration, plus exclusive in-house content from Fantasma Games and player engagement tools in later phases of the rollout.
The two roles are not symmetrical, and conflating them is where readers go wrong. EveryMatrix is a B2B iGaming supplier. Its modular platform does include player account management and payments products, so it can run the account and transaction layer where an operator buys those modules, but it is not the licence holder facing the player and does not answer to a gambling regulator for how Stake treats its customers. In the Stake arrangement it delivers content and the technical layer around it.
Stake is the operator. It runs the brand, holds the accounts, takes the bets, and carries the licence in each market where it accepts players. Everything a player experiences as “the casino” sits on Stake’s side of that line.
Why does Stake need this at all? Because regulated expansion is content-hungry in a very specific way. Entering a licensed market is not just a matter of flipping a geo-switch. Each jurisdiction has its own rules about which games may be offered, which studios are certified locally, how results are logged, and what has to be reported. Doing that market by market, studio by studio, is slow. Buying it as infrastructure is faster, and speed is what the deal is really purchasing.
How the plumbing works
Direct studio integration versus aggregation
A direct integration is a one-to-one technical and commercial relationship between operator and game studio, repeated for every studio. Each one needs a contract, revenue share terms, an API connection, test certification in each market, wallet and bonus integration, and ongoing technical support when something breaks at 2am on a Saturday.
Multiply that by 360 providers and the arithmetic becomes obvious. Aggregation collapses it: the aggregator does the one-to-many work on the supply side, then exposes one standardised interface on the operator side. New studios the aggregator signs become available downstream without the operator writing new code.
The trade-off is control. Direct deals give an operator better margins on high-volume titles, exclusive release windows, and a direct line to the studio’s roadmap. Most large operators run both: aggregation for breadth, a handful of direct relationships with the studios that drive the most turnover.
Why operators rarely build this in-house
Building an aggregation layer internally means becoming a casino platform provider as well as a casino. That is a different business with different staffing: integration engineers, certification specialists, compliance teams per jurisdiction, and a content acquisition function negotiating with studios full time.
Some very large operators have done it. Most conclude the capital is better spent on acquisition and retention, and rent the plumbing instead. There is no prestige in owning the pipes if your competitors rent better ones.
Licensing does not travel with the games
An aggregation deal does not license an operator anywhere. Each game and studio still needs certification in each jurisdiction that requires it, and the operator still needs its own licence from each regulator whose market it serves. The aggregator manages the compliance layer around the content; it cannot grant the operator permission to trade.
This is the single most expensive misreading of a press release like this one, and it is worth being blunt about. “Supports casino aggregation across regulated markets” means EveryMatrix can deliver content in a form that satisfies regulators in markets where Stake is licensed. It does not mean Stake is licensed in your market. Reporting on the deal describes Stake as gaining local licences across multiple territories, which is a process, not a finished state. If you want to know whether a given brand is authorised where you live, the only reliable answer comes from your regulator’s own list of licensees, not from a supplier announcement.
What the aggregator’s compliance layer does handle is real work: filtering the catalogue so only locally certified titles appear in a given market, maintaining the jurisdictional certifications with testing laboratories, adapting game behaviour to local rules such as mandatory spin durations or feature-buy bans, and feeding the regulatory reporting formats each authority demands. The same principle shows up every time a studio goes live in a new country: certification is granted market by market, which is exactly what makes a regulated market launch a meaningful signal about a studio rather than a formality.
Aggregator, direct deal or white label
Three supply models dominate, and they differ mainly in who does the work and how fast the operator moves.
| Model | Time to market | Content breadth | Who handles compliance | Operator control |
|---|---|---|---|---|
| Aggregator partnership | Fast, one integration | Very wide, hundreds of studios | Aggregator for content certification; operator for its own licence | Moderate |
| Direct studio integration | Slow, repeated per studio | Narrow per deal | Operator and studio jointly, per market | High |
| White-label platform | Fastest, brand on someone else’s stack | Whatever the platform carries | Mostly the platform holder, often on its own licence | Low |
White label is the one players most often misunderstand. In that model the brand on the website may not be the licence holder at all, which changes who you are actually dealing with if a dispute goes to a regulator.
What changes on the player’s screen
Aggregation makes libraries bigger and refresh faster, and it makes competing casinos look increasingly alike. A single aggregator typically supplies dozens of operators, so the same new release can appear across a dozen lobbies in the same week, sorted under the same provider filters.
That similarity is not laziness. It is the supply chain showing through. If two sites both run the same aggregation catalogue, their slot sections will converge on the same few hundred popular titles, and the real differences move elsewhere: payment methods, withdrawal speed, bonus terms, customer support, and whether the licence covers you.
Game fairness is unaffected by the aggregation layer. RTP, volatility and the RNG behind each round are properties of the game as built and certified by its studio. The aggregator transports the game; it does not reconfigure the maths. Where operators can influence RTP, it is through a studio-provided configuration option set at the game level, which jurisdictions increasingly restrict or publish. Aggregation neither creates nor hides that.
The concentration question, and which reading I’d back
Two readings of the aggregation trend are both defensible. The first: this is unglamorous efficiency. Plumbing consolidates because plumbing benefits from scale, studios reach more players through fewer doors, small developers get distribution they could never build alone, and nobody’s gameplay changes.
The second: a shrinking number of suppliers now decide which games reach the market at all. When one catalogue carries 45,000 titles from 360 providers, inclusion in that catalogue is close to a precondition for commercial existence, and the aggregator becomes a gatekeeper with pricing power over studios on one side and operators on the other.
Both are true; the second is the one that matters more over five years. Efficiency arguments describe the present state, while gatekeeping describes the direction of travel, and the direction is what players eventually feel as narrower genuine choice behind a wider apparent one. That said, the counter-argument has teeth: barriers to launching a studio have fallen, and aggregators compete hard for exclusive content, which is precisely why EveryMatrix bundles its own Fantasma Games titles into the offer. Whether that competition holds as the supplier tier consolidates is genuinely unsettled.
Checking a game library before you trust it
A supplier announcement tells you nothing about whether a casino is legal or safe for you. Three checks do more than reading any number of partnership headlines.
- Confirm the operator’s own licence for your jurisdiction on the regulator’s public register, not on the casino’s footer.
- Look for game-level testing by an independent laboratory such as eCOGRA or iTech Labs, and for published RTP figures in the game’s own info screen.
- Treat a large aggregator’s name as evidence about content supply only. It says nothing about local legality, withdrawal reliability or bonus terms.
Then read the deposit and withdrawal terms before the game list, because that is where the friction actually lives. And set a deposit limit before you need one: every licensed operator offers deposit, loss and session limits, plus cool-off and self-exclusion tools, and they work best when switched on early rather than in the middle of a bad run.
The open question in all of this is not technical. Aggregation clearly works, and Stake will get its catalogue. What nobody can tell you from a press release is which of the markets named in it will actually have Stake on the licensed list twelve months from now, and that is the only part of the deal that determines whether any of those 45,000 games are available to you at all.
About The Author