What a cashless casino payment system actually is
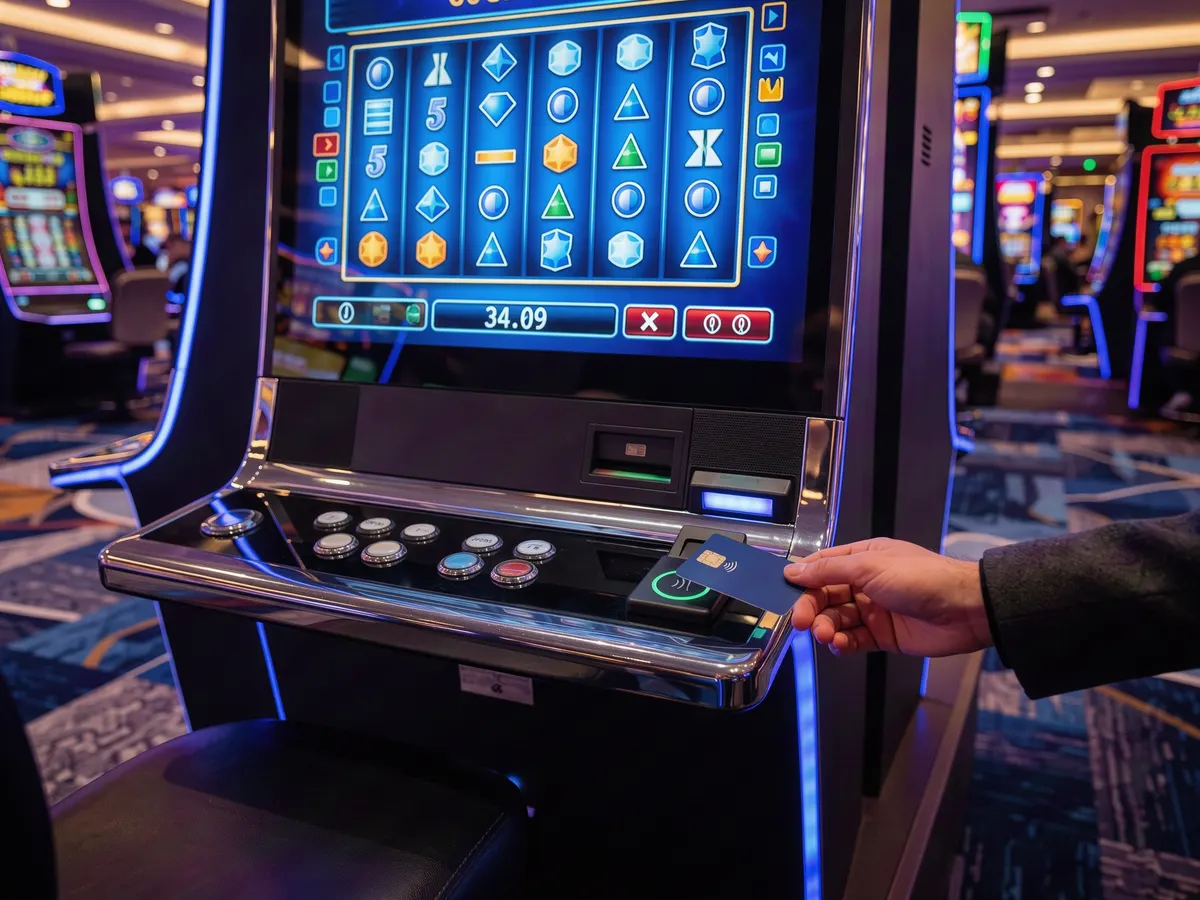
A cashless casino payment system replaces banknotes and printed vouchers with a card, account or phone app that holds your funds and moves them on and off a gaming machine electronically. In practice that means tapping or inserting a card at a slot cabinet instead of feeding in notes, and transferring a balance back to your account instead of queuing at the cage.
That is the clean definition, and it hides the condition most coverage skips: digitising a casino floor and digitising the money on that floor are two separate projects. They get announced in similar language, they often share the same back-end system, and they are frequently confused. The Swiss Casinos rollout that finished this month is a good illustration, because it is an example of the first kind and not the second.
Swiss Casinos’ ReelLink rollout, and what it does not cover
ReelLink is Swiss Casinos’ in-house technology for delivering online game content onto physical slot machines, and as of 13 October 2026 G3 Newswire reported the rollout complete across all four of the group’s venues: Casino Zurich, Casino Zürichsee in Pfäffikon, Casino Winterthur and Casino St. Gallen. It runs on 24 machines, with a further 17 planned before the end of the year, taking the group total to 41.
According to the same report, the platform first went live at Winterthur and Pfäffikon in December 2025 and was extended to Zurich and St. Gallen in July 2026. What it does is separate game content from the physical cabinet, so certified online titles can be pushed to approved machines in seconds and updated cabinet by cabinet. A floor can be refreshed at the pace of an online lobby rather than waiting months for new hardware to arrive. It plugs into the casino’s existing management system, leaving player tracking, accounting and the regulatory plumbing in place.
Nothing in that description is a payment change. The money still arrives however it arrived before. What ReelLink demonstrates is the architectural shift that makes cashless payments possible later: once the cabinet is a thin client hanging off a central system, the balance on it is already a database entry rather than a pile of coins. The casino management system that tracks every payout behind the scenes is the same layer a cashless wallet would sit on. Content came first because it is commercially urgent and regulatorily simpler. Payments follow, and in most jurisdictions they follow slowly.
From coin hoppers to paper tickets: how ticket in ticket out works
Ticket in ticket out technology, usually shortened to TITO, replaced coin payouts with a printed barcode voucher. Cash out of a slot machine and it prints a slip showing your balance; feed that slip into the next machine’s note acceptor and the balance transfers across. Redeem it at a kiosk or the cashier when you are done.
How TITO vouchers work
The ticket itself carries no value. It carries a validation number that the casino’s system matches against a recorded balance, which is why a lost ticket can often be traced and why a photocopied one is worthless. TITO ended coin hoppers, hopper jams, and staff walking buckets of change around the floor. It did not end cash: notes still go in the front of the machine, and tickets still have to be turned into notes at some point.
How card-based cashless play differs
Card-based cashless play removes the paper step entirely. Your balance lives in an account tied to a card or an app, and the machine reads it rather than printing it. Move to another game and there is nothing to carry. The trade-off is that you are now inside a closed-loop system: the funds are usable at that operator’s venues and nowhere else until you withdraw them, and getting them in and out involves identity checks that a ticket never required.
| Method | Where the balance sits | Moving between machines | Cashing out |
|---|---|---|---|
| Coin / note only | Physically in the machine | Carry coins or notes | At the machine or cage |
| TITO voucher | Casino system, referenced by a printed barcode | Insert the ticket into the next cabinet | Redemption kiosk or cage |
| Closed-loop card | Operator-held player account | Tap or insert the same card | Transfer to the account, then withdraw |
| Mobile wallet / NFC | Operator-held account, accessed by phone | Tap the phone at the cabinet reader | In-app transfer, cage-less |
Walking through a cashless casino card, step by step
The flow is the same at most operators that have deployed one, whatever the branding.
Funding your play
- Register the account. This is where AML and KYC checks happen, which is why cashless enrolment usually requires ID even if walking in with cash did not.
- Load funds. Cash at a kiosk or the cage, a bank transfer, or a debit card, depending on what the local regulator permits. Many jurisdictions restrict credit funding.
- Transfer to the machine. Tap or insert the card at the cabinet, or tap a phone against an NFC reader, and move an amount from the account balance onto the game.
- Play. The credit meter behaves exactly as it always did. The game itself, its RTP and its RNG are untouched by how the money got there.
Cashing out winnings
Cashing out moves the credit meter balance back to the account rather than printing a ticket, usually with one button press at the machine or in the app. From there you either leave it for the next visit, withdraw it as cash at a kiosk, or request a transfer to your bank. Withdrawal timing is where operators differ most: some pay instantly at a kiosk, others treat a bank payout like any regulated transfer, with verification and a settlement delay.
The operator’s case for casino payment innovation
Casinos invest in cashless systems mainly to reduce the cost and risk of handling physical cash. Every note on a floor has to be counted, transported, reconciled, insured and secured, and every one of those steps carries staff time and theft exposure. Removing paper tickets also removes jammed printers, reprint disputes and redemption queues.
The second driver is data. A card-based system attaches every transaction to an identified account, which gives the operator a continuous view of play rather than the gaps that cash creates. That feeds loyalty programmes and the kiosk and mobile tools operators use to keep players engaged, and it also makes AML reporting considerably easier, since suspicious patterns are visible in a ledger instead of inferred from a cash drawer. Hygiene arguments gained weight after 2020 and are still cited, though they were never the main economic case.
Any specific figure on cash-handling costs or transaction speed varies enormously by venue size and jurisdiction, so treat industry averages with suspicion unless the operator or regulator publishing them is named.
What changes for the player at the machine
For players, cashless payments mainly buy speed and remove small frictions: no fumbling for the ticket that fell behind the seat, no walking to a kiosk between games, no carrying a visible wad of notes through a car park. Funds held in an account are safer from simple loss or theft than notes in a pocket.
The cost is awareness. A credit meter you topped up by tapping a card does not feel like the notes you counted out at the cashier, and the research on how payment form affects spending in retail generally points the same direction: the less physical the money, the easier it is to spend more of it without noticing. Nothing about a cashless system changes the house edge, and nothing about it changes the fact that over enough rounds the operator’s margin wins. It only changes how quickly you can put the next stake in.
Which makes the limit tools worth using rather than skipping. Most cashless wallets let you set a deposit cap, a loss cap or a session reminder at enrolment, and those settings are far more useful set in advance than reached for mid-session. If play stops being entertainment, the same account that holds your balance will usually also offer a cool-off or self-exclusion option.
Where this sits next to online payment rails
The land-based shift runs roughly a decade behind the online one, and it is borrowing from it. Digital casino payments online settled on e-wallets, instant bank transfers and card tokenisation years ago, and closed-loop venue wallets are now reaching for the same conveniences: a stored balance, a tap, a cage-less cashout. The direction of travel is clear enough.
What is not settled is whether a single wallet will ever work across both. Land-based and online licences are usually separate instruments with separate funding rules, and in several markets moving a balance between them is explicitly restricted. So the honest read on ReelLink is narrow: it shows a Swiss operator can now refresh four floors at online speed, which is a real change to how games reach a cabinet. Whether the money follows the same path, and under what limits regulators will allow it to, is the question still waiting for an answer.
About The Author